

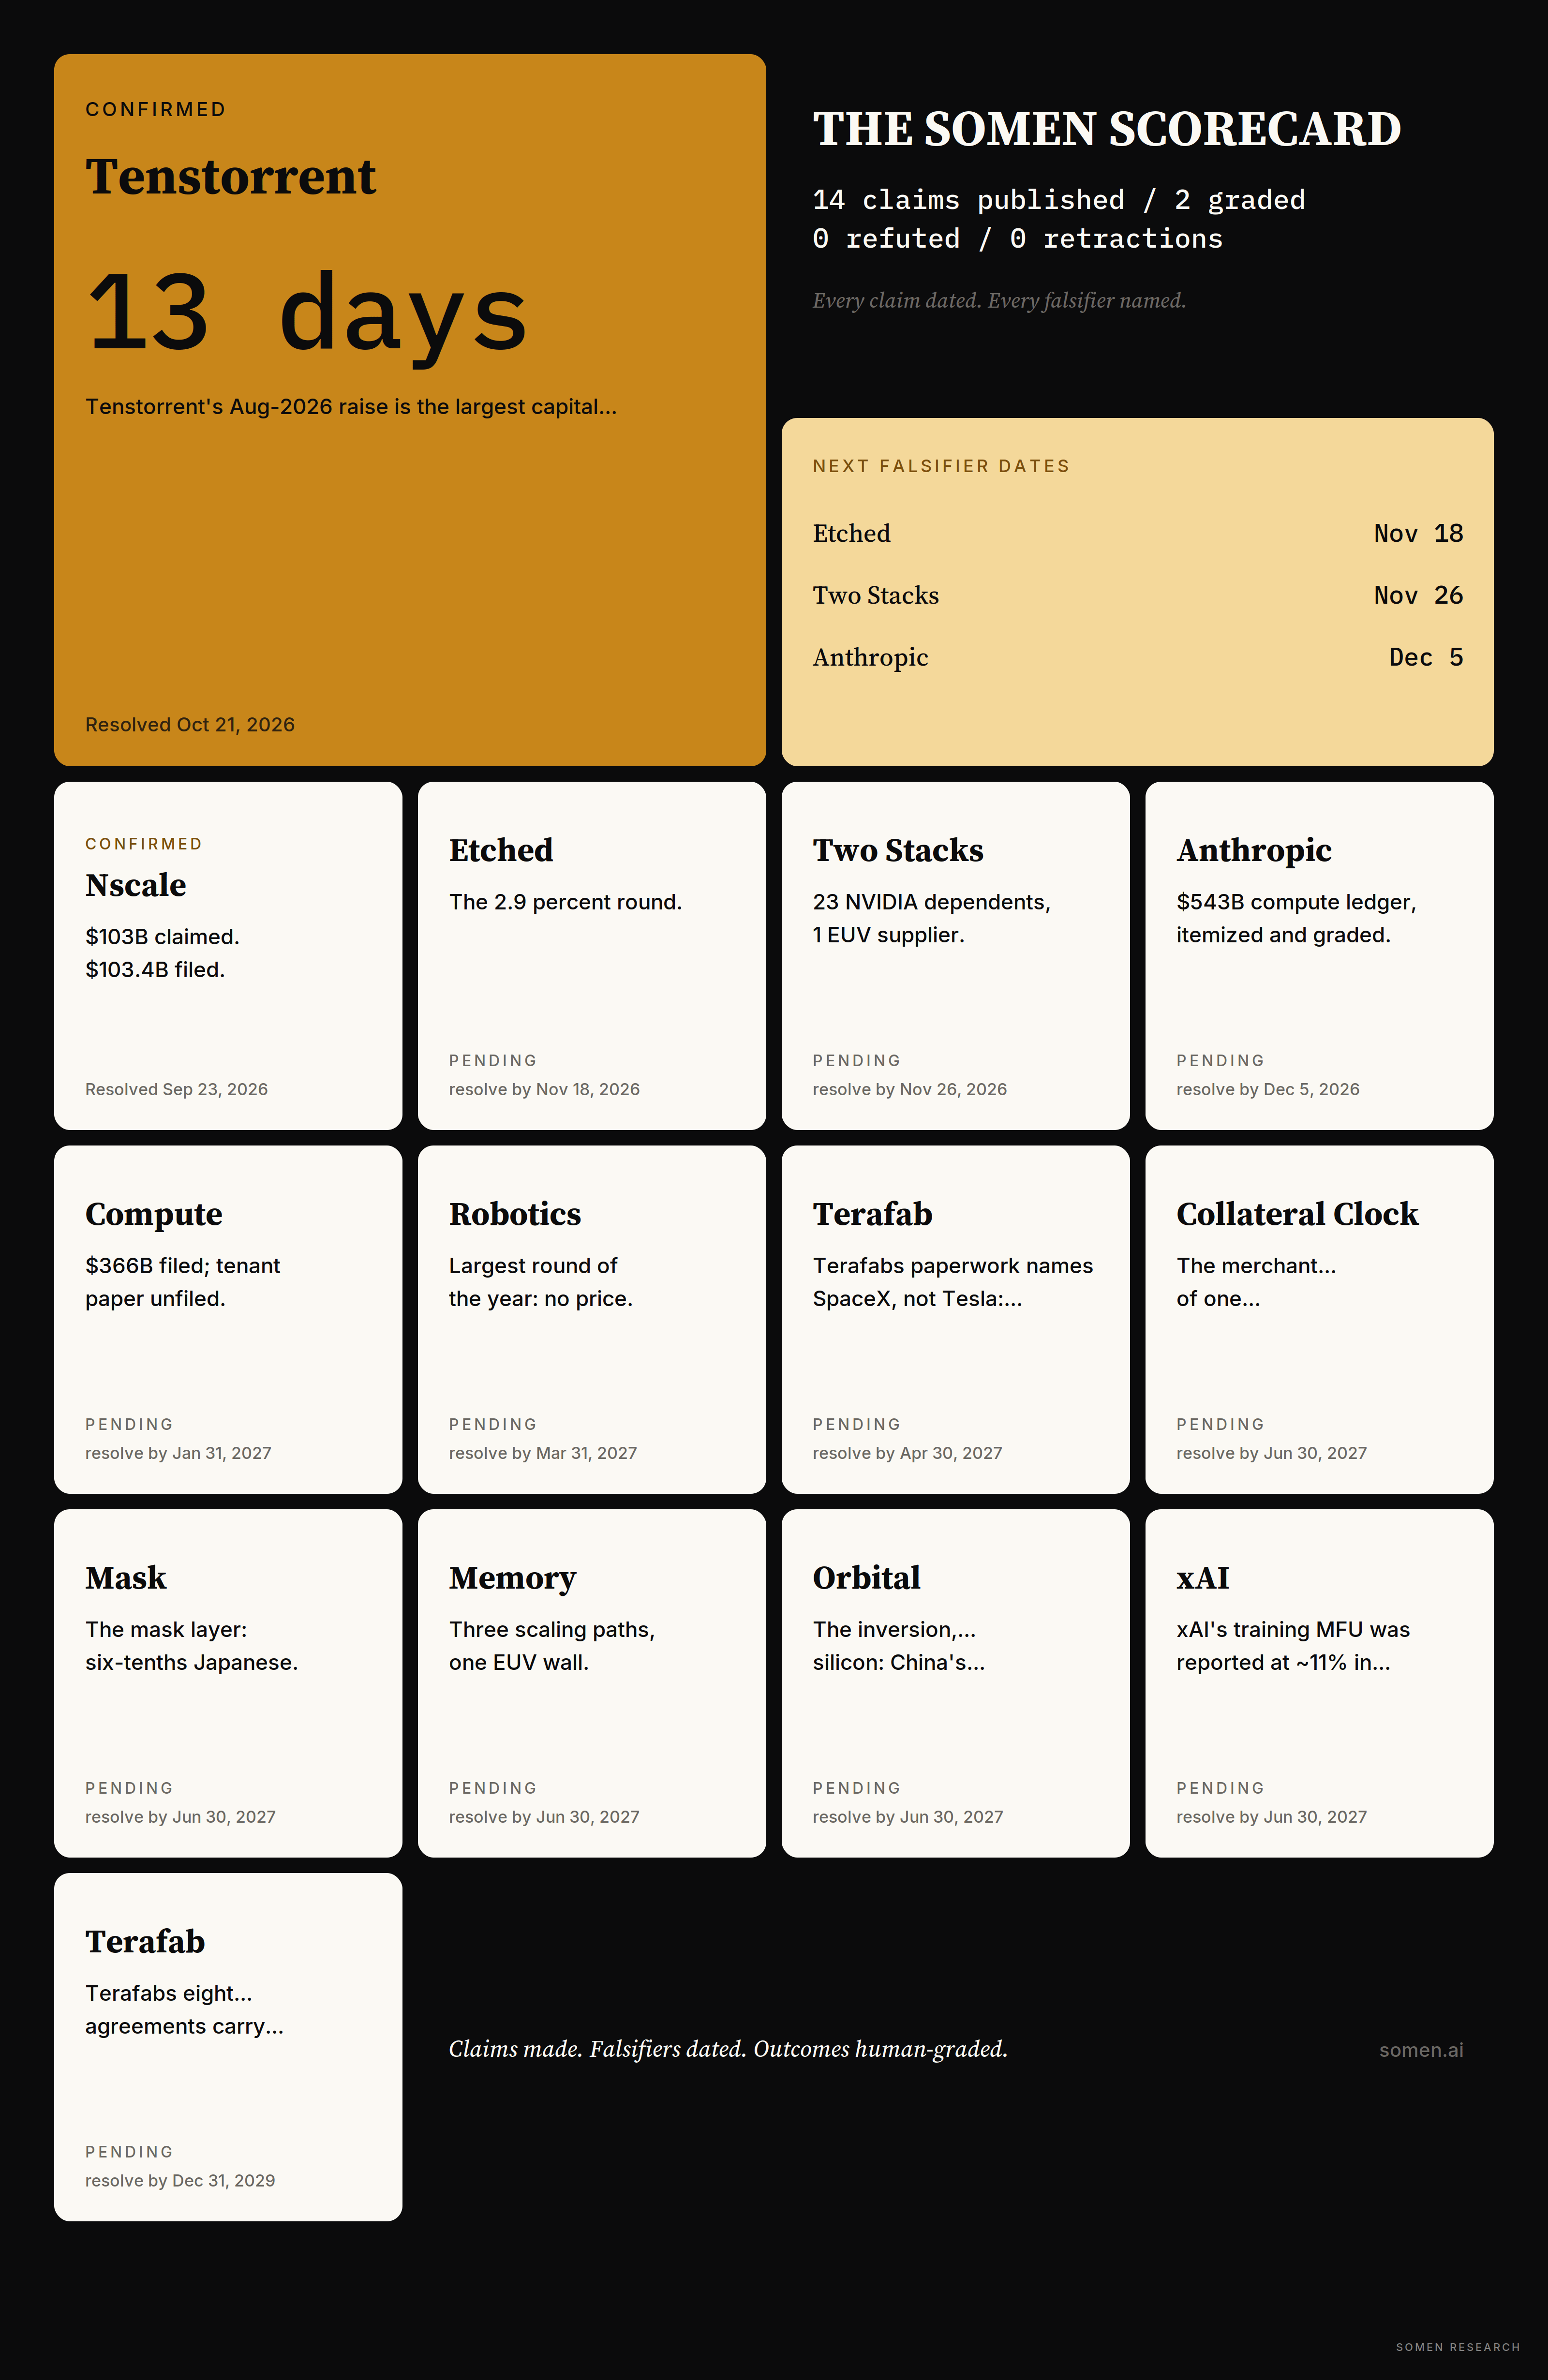
One entry per published teardown: the core claim it rests on, what would refute it, and the recorded outcome. Outcomes are human judgment recorded by the operator; nothing on this page is inferred or graded automatically.
The ledger
Confirmed
Nscale (published Sep 7, 2026)
Confirmed Sep 23, 2026. Resolve-by was Dec 31, 2026.
Piece: nscale-103-billion-claimed-21-million
The claim.
Nscale tells IPO investors ~$103B in contracted revenue against ~$100M a quarter (bookings or revenue, the relays do not say); the named deals sum to ~$51B (the August figure), leaving ~$52B with no named counterparty; the only audited lines anywhere in the group are ~$21M FY2024 (Norwegian, KPMG); Aker’s equity-method note expects results near administrative expenses through the development phase
What would refute it.
FY2025 accounts (due 30 Sep 2026) and/or the S-1 show booked revenue ramping toward the ~$18B annualized contracted claim - or they do not; Aker’s next carrying-value note is the second test
Outcome.
Resolved early by the S-1 (filed 2026-09-18, eleven days after publication). The fork held at filing grade on both sides: TCV $103.4B active+contracted filed take-or-pay vs the $103B investor-doc claim; audited revenue $19.1M FY2024 / $33.0M FY2025 / $140.6M H1-2026. The piece ~$21M FY2024 was the NOK census approximation of the audited $19.1M, corrected in place 2026-09-19. The unnamed $52B resolved to Microsoft (~$43.8B SOWs through 2033); concentration filed sharper (MSFT+Anthropic 86% of TCV). Ramp test: H1-2026 annualizes ~$281M vs the ~$18B implied - direction arrived, magnitude did not; RPO $34.5B recognition is the standing watch. Aker Q3 carrying note pending (corroborative; Q2 carried at the $14.6B Series C post).
Evidence:
Nscale: $103 Billion Claimed, $21 Million Filed

Update, 19 September 2026: the S-1 landed. Nscale Limited, the UK topco the May reorganization inserted, filed its Form S-1 on 18 September (NYSE: NSCL). Most of what this piece asked for arrived by filing. Audited revenue: $19.1 million FY2024, $33.0 million FY2025, $140.6 million H1 2026, against a $1.02 billion H1 net loss. The $103.4 billion figure …
Tenstorrent (published Oct 8, 2026)
Confirmed Oct 21, 2026. Resolve-by was Apr 30, 2027.
Piece: tenstorrent-1-29-billion-filed-no-price
The claim.
Tenstorrent’s Aug-2026 raise is the largest capital event in its filed history ($1,286,829,662 to 134 investors) yet carries no price anywhere: the Form D discloses none, the circulating $3.2B is an unclosed Nov-2025 talks figure ($800M, Fidelity-led), and the $108.35 listing price is an indicative model that a vendor (not the filing) turns into a $5.76B implied valuation via an assumed share count. If the talks figure held as pre-money, the filing would represent an undisclosed ~28.7% primary stake - implausible, so the mark moved or the filing aggregates.
What would refute it.
Any disclosed post-money for the Aug-2026 raise (named round coverage, fund portfolio disclosures, or an S-1). Nearest watchpoints: the monthly Fidelity holdings listings and the registered-fund marks already in the wild – two Fidelity portfolios carried the same Series D-1 47.6% apart ($75.63 May 31 vs $111.61 Jun 30, per AltStreet); ARK $81.39->$89.42.
Outcome.
RESOLVED Oct 19: Series E $1.5B at $6.2B post (Bloomberg/Company). The fork falsifier (any disclosed post-money) is MET. The published piece called the gap between the $1.29B Form D (no valuation) and the $3.2B circulating figure; the answer is $6.2B nearly double the talks figure. Napkin: 1500/6200 = 24.2 percent.
Evidence:
Pending
Etched (published Aug 18, 2026)
Pending. Resolve by Nov 18, 2026.
Piece: etched-the-29-percent-round
The claim.
Etched’s $300M Series C at a claimed $10.3B post-money bought the entire syndicate roughly 2.9% of the company - the thinnest new-money slice of the 2026 AI-silicon set, at the only company in that set with no shipped product. The percentage is arithmetic against the company’s own round figures; the valuation is a claim.
What would refute it.
A disclosed cap table, share count, or next-round/IPO filing showing the C syndicate’s new-money stake materially above ~3%, or round economics (e.g. a large secondary component) that overturn the napkin. Post-publication datapoint already on record: the Aug 19 $700M Series D at $21B (a sibling 3.3% napkin), resolution judgment reserved to the operator.
Two Stacks (published Aug 26, 2026)
Pending. Resolve by Nov 26, 2026.
Piece: two-stacks-the-ai-compute-supply
The claim.
Both AI compute stacks converge at one chokepoint: every advanced-node path in the Western graph routes through ASML’s sole-source EUV, which itself depends on two sole-source German suppliers (Trumpf lasers, Zeiss SMT optics). The chain narrows as it deepens - 23 direct NVIDIA dependents, 13 TSMC dependents, 1 EUV supplier, 2 tool suppliers - and the newest cross-stack evidence (Xiaomi’s XRING self-sufficiency chips all fabricated by TSMC) deepened the dependency rather than thinning it.
What would refute it.
Volume Chinese sub-7nm production without ASML-serviced DUV (SMIC 5nm-class at yield), a Chinese EUV-class scanner in production use, or a Western frontier training run booting at scale on zero TSMC-fabricated accelerators; also refuted in part if the graph-derived counts (23 NVIDIA / 13 TSMC / 1 ASML / 2 German suppliers) fail re-derivation as the graph evolves.
Memory (published Sep 10, 2026)
Pending. Resolve by Jun 30, 2027.
Piece: memory-after-the-sold-out-years
The claim.
Inside the memory oligopoly the post-2027 scaling paths diverged: Samsung committed the first High NA memory insertion (DRAM HVM by 2028), SK hynix hedges with one High NA tool plus a fleet-doubling 0.33NA order (KRW 11.95T), and Micron made no High NA commitment at all - while the Chinese challengers legally cannot buy EUV at any price and the next mask standard is being set without them.
What would refute it.
Micron announces High NA production insertion before 2028 (fork collapses into a rush); Samsung’s 2028 date slides toward 2030 without comment (positioning, not commitment); memory cell design stalls or 3D stacking accelerates (High NA loses purpose for memory); AI capex rolls over (fork inverts into an over-investment contest); the 2027 HBM contract round clears materially below the +50-140% forecasts (demand-crack wins, insertion dates slip).
Anthropic (published Sep 15, 2026)
Pending. Resolve by Dec 5, 2026.
Piece: anthropics-543-billion-compute-ledger
The claim.
Anthropic’s compute-procurement program, itemized and graded, totals ~$543.1B across ten priced commitments out of fourteen (census of 2026-09-14; a program total, not unique obligations): $64B FILED across two filings naming Anthropic PBC - the TeraWulf 8-K lease ($19B firm rent, 20yr/401MW at the former Century Aluminum smelter site, rent on phased delivery from late 2027) and SpaceX’s 424(b)(4) ($45B in filed CANCELLABLE terms: $1.25B/mo through May 2029, ~325K GPUs, 90-day mutual exit after month 3) - $180B company-confirmed, $299.1B press-grade (Riot included: dollars landlord-stated, tenant named only by reporting; a row grades by its weakest element); backed floor $244B; evidence quality inverse to headline size (Google ~$200B, the largest line, never stated by any party); Series H bought 6.7% at $965B post (65/965), last company-written revenue $47B (May, the round post itself) vs relay-carried $65B (end-July); zero issuer Form Ds behind the $65B raise (111 vehicle filings, re-run Sep 14); the federal arc: $200M CDAO ceiling Jul 2025, Pentagon work terminated + supply-chain-risk designation Feb 2026, OneGov terminated, two lawsuits Mar 9, the Aug 27 ruling vacating the designation as unlawful retaliation (appeal expected); every published tally reconciled in-piece (ValueAdd $275B+ / Decoding Discontinuity $254B-~$450B / The Information ~$517B: gaps are scope and vintage, not fact).
What would refute it.
The public S-1’s audited compute-commitments note and revenue line: if filed+company commitments print materially below ~$244B, or audited run-rate prints materially below the relay-carried $65B end-July figure (last company-written: $47B, May), the tier census or the trail was wrong; the napkin (65/965 = 6.7%) fails only if the round’s actual post-money differs from the company’s stated $965B; the risk factors grade against the pre-disclosure record (the Aug 6 congressional letter, the Aug 27 ruling, the essay’s committed evaluator names); the designation litigation (appeal + D.C. companion) runs to the listing.
Mask (published Sep 22, 2026)
Pending. Resolve by Jun 30, 2027.
Piece: the-bigger-stencil-asml-photomask
The claim.
The photomask layer is the semiconductor chain’s newest structural chokepoint – a merchant tool stack six-tenths Japanese with a two-for-two Japanese blank duopoly – committed on paper to a 12-inch, 2031/2033 re-tool that its own supply base has not yet subscribed to, while the US’s largest merchant shop waits on economics and China’s DUV multi-patterning workaround compounds its dependence on the very stack it cannot localize (blanks, writers, actinic inspection, pellicles) under two live export-control perimeters.
What would refute it.
2031 pilot or 2033 readiness slips or is abandoned; ASML/TSMC confirm existing High NA tools retrofit to 6x12 (two-format re-tool burden collapses); a second actinic patterned-mask inspection vendor ships at production grade; Samsung’s 2028 memory or TSMC’s 2030 dated commitment walks back; no named tool-vendor contracts by the 2027 SPIE cycle (the uncommitted-supply-base test); China joins large-format standard-setting, ships production EUV masks, or domestic blank production moves off zero.
Robotics (published Sep 29, 2026)
Pending. Resolve by Mar 31, 2027.
Piece: robot-marks-not-publicly-computable
The claim.
In the robotics sector the multiple measures distance from audit, not quality of the business: ten marks rest on ten different instruments (filed, customer-announced, company-announced, people-sourced, single-aggregator), none audited the same way, and the year’s largest round has no public price at all.
What would refute it.
Any of: audited filings showing the industrial demand the private marks assume (UBTech narrowing to profit, Unitree domain mix shifting from 73.6% research); the Dogotix Dec-31 1,000-IRON/month clock met with the completion 6-K; the Unitree lockup/first secondary print holding the 0B debut; an AgiBot prospectus range underwriting the 35-45x ask on checked books; an Atoms price surfacing by any route.
Compute (published Oct 6, 2026)
Pending. Resolve by Jan 31, 2027.
Piece: compute-financing-ledger
The claim.
The committed-vs-graded fork: sellers and a handful of landlords file their compute paper; the tenant-side commitments are mostly unfiled; the utilization spread is the tenant unit-cost problem and the leading walk indicator
What would refute it.
NVIDIA Q3 guarantee/commitment lines flat or grown (Nov 18); the Anthropic S-1 compute-commitments note; any Stargate-class walk
Terafab (published Oct 12, 2026)
Pending. Resolve by Apr 30, 2027.
Piece: terafab-paperwork-says-spacex
The claim.
Terafabs paperwork names SpaceX, not Tesla: all four registry entities (TERAFAB LLC DE 3913340; TERAFAB TEXAS LLC TX 0806741990; Terafab AI LLC TX 0806598568 at 1 Rocket Rd Starbase; WIT Tech LLC TX 0804854926 Brownsville) carry SpaceWorld addresses and none an Austin one; the S-1/424B4 carries no Terafab dollar figure; the only signable number, the $5B county minimum, has an unsigned SpaceX line.
What would refute it.
A filing booking Terafab capital (the SPCX Q3 10-Q due around November 2026 is the first candidate), a Tesla 10-K or earnings call booking Terafab capex or naming a Terafab entity, the executed county agreement with a signature on the $5B minimum line, or JETI documents naming applicant entities other than the four on file.
xAI (published Oct 14, 2026)
Pending. Resolve by Jun 30, 2027.
Piece: xai-780000-gpus-may-efficiency-number
The claim.
xAI’s training MFU was reported at ~11% in early May 2026 (The Information; an internal memo confirmed it, the president calling it ‘embarrassingly low’) against a reported hyperscaler band in the low-to-mid 40s - IF like-for-like, roughly 4x throughput on the table, with BF16-vs-FP8 and scale caveats. By Oct 7: installed base ~780k per Musk’s Sep 25 census (Colossus 2 alone scheduled to 1.21M year-end, last tranche conditional; fleet ~1.44M if it lands); MFU not refreshed since May; the Anthropic tenancy is a documented conflict (S-1: $1.25B/mo through May 2029, 90-day exit vs Musk May 28, a week after the May 21 filing coverage: short-term at SpaceX’s request); the hosting book is a forward stack (~$1.4B/mo billed today, ~$3.43B/mo run-rate once the December tranche lands).
What would refute it.
Any refreshed or disclosed MFU for the current (Blackwell-era) fleet; Nicolls’s target was months away, not years. A reading above 25% on a like-for-like definition resolves the fork.
Terafab (published Oct 15, 2026)
Pending. Resolve by Dec 31, 2029.
Piece: terafab-tax-break-per-job
The claim.
Terafabs eight executed school-tax agreements carry $1,660.4M of M&O relief through 2046 against the filings own employment figures (617 + 383 = 1,000 direct permanent, the per-phase-vs-cumulative ambiguity flagged) - $1.66M per filed job; even the most generous reading (4,000) leaves $415K per job.
What would refute it.
The 2029 hiring test: Iola schedules all 383 jobs for 2029 and Anderson-Shiro reaches the tax rolls in 2029-30. Hiring materially above 4,000 direct jobs by then, or abandonment/phase slippage before placement, resolves the claim either way.
Orbital (published Oct 20, 2026)
Pending. Resolve by Jun 30, 2027.
Piece: two-stacks-in-orbit
The claim.
The inversion, organizational not silicon: China’s orbital compute is real (20 satellites across two launches, the only multi-satellite compute constellation flying) while its silicon opacity dissolves only from the edge (Oct-14 batch named XFEON’s StarCore S1; a MetaX GPU flew in July; no Ascend or Cambricon flagship part flies in any compute constellation); the Western constellations are filings (1.14M satellites requested as ceiling counts, all three verified) with merchant silicon announced (NVIDIA’s space module) and only a demo satellite plus two hosted Axiom nodes flying.
What would refute it.
An Ascend or Cambricon part flying in a compute constellation (Cambricon’s Feb-2026 investor denial is one side); New Glenn’s December return flying or slipping; the FCC ruling on the Sunrise amendment (waiver treatment the tell); SenseTime’s four sats and Three-Body’s third group by year-end 2026; 2027: first Space.IDC G1, Pearl verification, Starmind first launches, NVIDIA module first flight.
Collateral Clock (published Oct 27, 2026)
Pending. Resolve by Jun 30, 2027.
Piece: gpus-backing-ai-debt-halve-every-four-years
The claim.
The merchant replacement cost of one H100-equivalent of NVIDIA compute halves every ~49 months (A100 $38,058 Nov-2020 -> B300 $17,019 Aug-2025, per Epoch AI); market-to-replacement multiples split on that clock (CRWV 1.2x vs NBIS 8.9x).
What would refute it.
Rubin merchant price below ~$12,500/H100e = the clock holds (one half-life after the H100); flat-to-up = slowed. (2) MUSK’S GUPPY CLAIM (Oct 25, verbatim): ‘200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many’ - scored as consolidation/distress/failure events across the tracked neocloud set by late 2027. Watchpoints: Rubin pricing; second-hand H100 prints; CoreWeave Nov 9 + Nebius Nov 10 earnings; SpaceX 10-Q capital-commitment language on the $40B.