

The short version
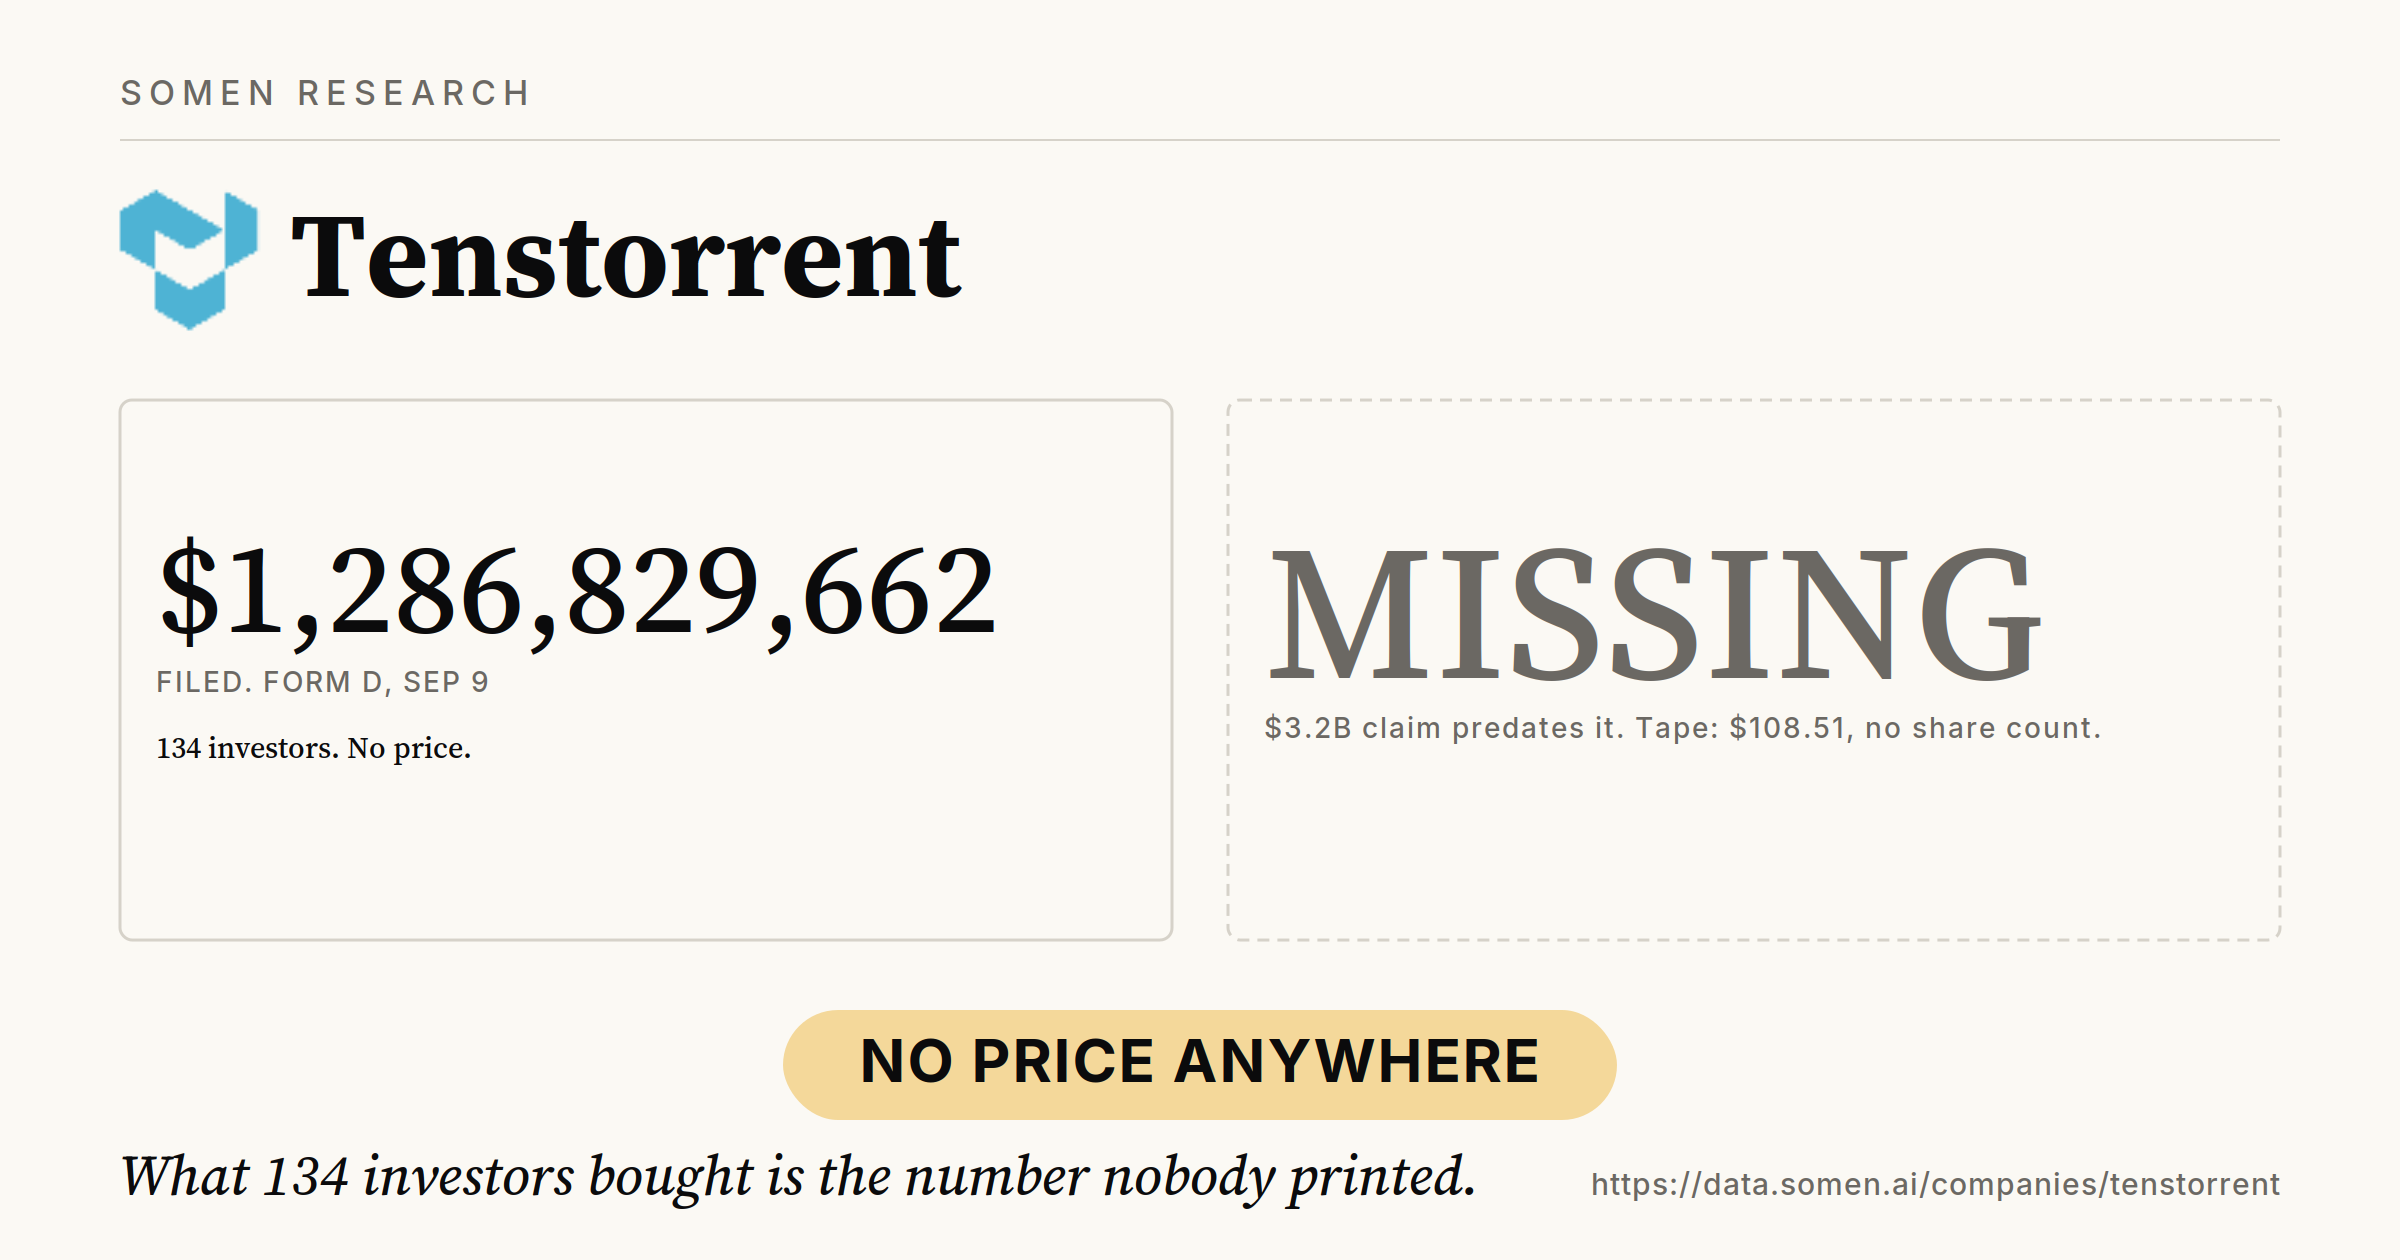
Tenstorrent Holdings filed a Form D on Sep 9, 2026: $1,286,829,662 sold to 134 investors of a $1,416,015,946 equity offering, first sale Aug 26.
The filing discloses no valuation, no price per share, and no investor names. Form D never does.
The circulating $3.2 billion is not a mark: it is a November 2025 talks figure - an $800M raise, Fidelity-led - that was never announced closed.
The listing’s $108.51 (Oct 7) is an indicative model price, not a trade. A vendor can turn it into a valuation by assuming a share count. The filing cannot, because it publishes neither.
Filed capital, unclosed talks, and an indicative price. The arithmetic cannot run from the record.
The fork
The talks side. The number that circulates is $3.2 billion - but the coverage it rides on says, in its own body, that Tenstorrent was “in talks to raise $800m at a $3.2bn pre-money valuation led by Fidelity Management in November 2025.” No closed round was ever announced at that number. The same coverage reports early-stage takeover conversations with Intel and Qualcomm. The last closed round on record is the $693M Series D, December 2024 - a $2B pre-money, about $2.6B post, and itself part note: $593M of equity plus a $100M convertible from 2023 that converted in. Everything between that post and today is talk.
The filed side. The $1.29 billion notice is the largest capital event in the company’s filed history - the $1.416 billion offering is 21.5x the fully-sold $65.8M July-2025 notice, and the amount sold is roughly 2x the $693M December-2024 Series D. Rule 506(b), equity securities, $129.2M still on offer. The filing says capital arrived. It does not say at what price.
The indicative side. The listing carries a daily price series - 122 days of it, latest $108.51 - built from blended transaction and quote data, not from trades you could audit. Two independent vendors run cents apart on the same days (Stock Analysis: $108.48-51, and our own capture ticked $108.35 to $108.51 across the week), which tells you the series is real but the instrument is a model. And the model becomes a number only when someone adds a share count: Stock Analysis prints an implied $5.76 billion, dated Aug 26 - the day the filing’s first sale closed - using an assumed share count the filing never discloses. A vendor can cross that bridge. The record cannot.
The napkin
IF the unclosed $3.2B talks figure held as pre-money:
$1,286,829,662 primary would buy 1,286.8 / (3,200 + 1,286.8) = 28.7% of the company.No disclosed investor group claims a stake near that - though Form D would not show it either way, and a lead, a club, or a converting instrument can absorb that much quietly (the last round itself closed a $100M note into equity). The implausibility is this desk’s prior, not a record fact.
Run the same conditional off the CONFIRMED December post instead - $2.6B pre - and $1,286.8M buys 1,286.8 / (2,600 + 1,286.8) = 33.1%: dilution larger, price still unpublished.
So the number moved before the money did, or the filing is not one primary round. The napkin stays conditional. That is the finding.
Why it matters
For calibration, the clean peer priced its paper: Etched’s $700M Series D printed a $21B valuation in round coverage. Groq - no longer a challenger so much as an NVIDIA-systems operator since its licensing deal - still printed $3.5B on its August round. (“Post” at both is the standard reading of “valued at,” not a term either company printed.) Tenstorrent moved roughly double their capital and printed none.
The practical point for an allocator: every “at a $X billion valuation” restatement of this round you read between now and a priced disclosure is invention - a talks figure repeated as a mark, or a vendor’s assumed share count presented as a valuation. The company raised real money from 134 real buyers. What they bought remains the only number nobody printed.
The checkable mechanics, if you want them: EDGAR full-text search on “Tenstorrent” surfaces the notices as they land; Fidelity’s public monthly holdings listings carry Tenstorrent Series D1/D2/C1 at value level (the Sep 9 listing: $18.4M for D-1) - institutional marks are public monthly, even when per-share terms are not; and any named-round coverage would carry the post-money that resolves the fork. None of that requires this desk. That is the point of a falsifier.
The falsifier
Any disclosed post-money for the Aug-2026 raise - named round coverage, fund portfolio disclosures, or an eventual S-1 - resolves this fork. Tracked on the public scorecard, resolve by Apr 30, 2027. The near-term watchpoints are already in the wild: two Fidelity portfolios valued the same Series D-1 at $75.63 (May 31) and $111.61 (June 30) - 47.6% apart - and ARK Venture marked it $81.39 then $89.42. Registered funds are the only independent pricing evidence on record, and they disagree with each other.
Sources
SEC EDGAR - Tenstorrent Holdings Form D, Sep 9 2026 (CIK 2031944) - amounts sold/offered, investor count, first-sale date, prior-round comparisons
The Next Web - Intel/Qualcomm coverage - the talks figure ($800M at $3.2B pre, Nov 2025), the takeover conversations, the Dec-2024 Series D baseline
Clarity (Hiive) - Tenstorrent listing - the $108.51 indicative price, Oct 7 2026 capture (series moves daily)
Stock Analysis - Tenstorrent - the independent price series (cents apart) and the $5.76B implied valuation dated Aug 26 2026
Fidelity - Select Technology Portfolio holdings, Sep 9 2026 - Tenstorrent Series D1/D2/C1 at value level
AltStreet - the Form D, both notices, and the fund marks - the 47.6% Fidelity fork ($75.63 vs $111.61) and ARK’s marks
BetaKit - Series D close - $2B pre / $2.6B post, $593M equity + $100M converted note
Numbers derived from the SOMEN graph at publication.
- The SOMEN Desk